Chiến Lược Phân Kỳ Hội Tụ (MACD) trong Bot Auto Trading Forex với Python
Mục lục bài viết
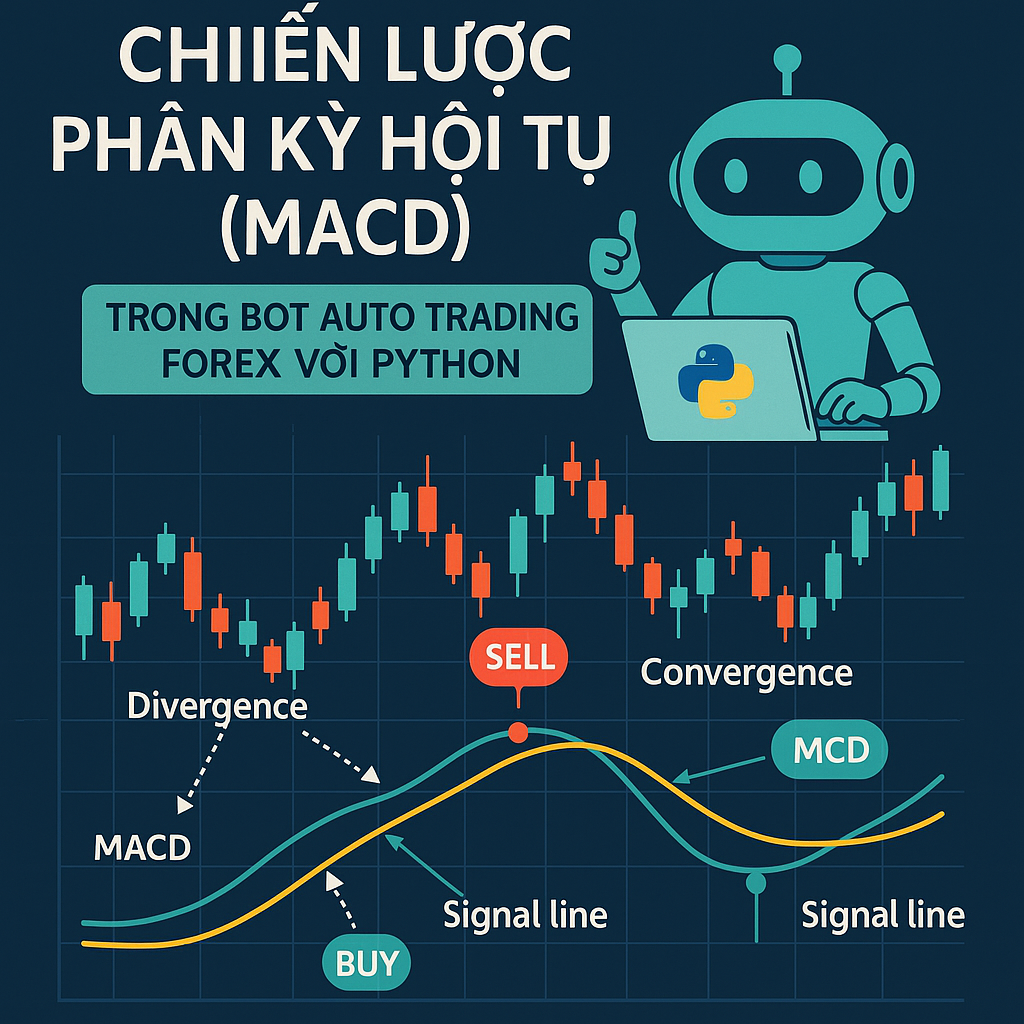
Chiến Lược Phân Kỳ Hội Tụ (MACD) trong Bot Auto Trading Forex với Python
MACD (Moving Average Convergence Divergence) là một trong những chỉ báo kỹ thuật phổ biến nhất trong phân tích kỹ thuật Forex. Trong bài viết này, chúng ta sẽ tìm hiểu cách xây dựng bot giao dịch tự động sử dụng chiến lược MACD với Python.
Tổng quan về MACD
MACD là gì?
MACD là một chỉ báo động lượng theo xu hướng, được phát triển bởi Gerald Appel vào cuối những năm 1970. Chỉ báo này đo lường mối quan hệ giữa hai đường trung bình động (Moving Averages) của giá.
Các thành phần của MACD
MACD bao gồm 3 thành phần chính:
- Đường MACD (MACD Line): Chênh lệch giữa EMA 12 và EMA 26
- Đường Signal (Signal Line): EMA 9 của đường MACD
- Histogram: Chênh lệch giữa đường MACD và đường Signal
# Công thức tính MACD
MACD Line = EMA(12) - EMA(26)
Signal Line = EMA(9) của MACD Line
Histogram = MACD Line - Signal Line
Cài đặt môi trường
Thư viện cần thiết
# requirements.txt
pandas==2.1.0
numpy==1.24.3
ccxt==4.0.0
ta-lib==0.4.28
matplotlib==3.7.2
python-binance==1.0.19
Cài đặt
pip install pandas numpy ccxt ta-lib matplotlib python-binance
Lưu ý: TA-Lib yêu cầu cài đặt thư viện C trước. Trên Windows, tải file .whl từ đây.
Xây dựng chỉ báo MACD
Tính toán MACD từ đầu
import pandas as pd
import numpy as np
from typing import Tuple

class MACDIndicator:
    """
    Lớp tính toán chỉ báo MACD
    """

    def __init__(self, fast_period: int = 12, slow_period: int = 26, signal_period: int = 9):
        """
        Khởi tạo MACD Indicator

        Args:
            fast_period: Chu kỳ EMA nhanh (mặc định: 12)
            slow_period: Chu kỳ EMA chậm (mặc định: 26)
            signal_period: Chu kỳ EMA cho Signal Line (mặc định: 9)
        """
        self.fast_period = fast_period
        self.slow_period = slow_period
        self.signal_period = signal_period

    def calculate_ema(self, data: pd.Series, period: int) -> pd.Series:
        """
        Tính toán Exponential Moving Average (EMA)

        Args:
            data: Dữ liệu giá
            period: Chu kỳ EMA

        Returns:
            Series chứa giá trị EMA
        """
        return data.ewm(span=period, adjust=False).mean()

    def calculate(self, close_prices: pd.Series) -> pd.DataFrame:
        """
        Tính toán MACD, Signal và Histogram

        Args:
            close_prices: Series chứa giá đóng cửa

        Returns:
            DataFrame chứa MACD, Signal và Histogram
        """
        # Tính EMA nhanh và chậm
        ema_fast = self.calculate_ema(close_prices, self.fast_period)
        ema_slow = self.calculate_ema(close_prices, self.slow_period)

        # Tính đường MACD
        macd_line = ema_fast - ema_slow

        # Tính đường Signal
        signal_line = self.calculate_ema(macd_line, self.signal_period)

        # Tính Histogram
        histogram = macd_line - signal_line

        # Tạo DataFrame kết quả
        result = pd.DataFrame({
            'MACD': macd_line,
            'Signal': signal_line,
            'Histogram': histogram
        })

        return result
Sử dụng thư viện TA-Lib
import talib

def calculate_macd_talib(close_prices: np.array) -> Tuple[np.array, np.array, np.array]:
    """
    Tính MACD sử dụng TA-Lib

    Args:
        close_prices: Mảng giá đóng cửa

    Returns:
        Tuple (macd, signal, histogram)
    """
    macd, signal, histogram = talib.MACD(
        close_prices,
        fastperiod=12,
        slowperiod=26,
        signalperiod=9
    )

    return macd, signal, histogram
Chiến lược giao dịch MACD
1. Chiến lược giao cắt (Crossover Strategy)
Chiến lược cơ bản nhất: mua khi MACD cắt lên Signal, bán khi MACD cắt xuống Signal.
class MACDCrossoverStrategy:
    """
    Chiến lược giao dịch dựa trên giao cắt MACD và Signal
    """

    def __init__(self, macd_indicator: MACDIndicator):
        self.macd_indicator = macd_indicator
        self.position = None  # 'long', 'short', hoặc None

    def generate_signals(self, data: pd.DataFrame) -> pd.DataFrame:
        """
        Tạo tín hiệu giao dịch

        Args:
            data: DataFrame chứa dữ liệu giá OHLCV

        Returns:
            DataFrame với cột 'signal' (1: mua, -1: bán, 0: giữ)
        """
        # Tính MACD
        macd_data = self.macd_indicator.calculate(data['close'])

        # Khởi tạo cột signal
        signals = pd.DataFrame(index=data.index)
        signals['signal'] = 0
        signals['MACD'] = macd_data['MACD']
        signals['Signal'] = macd_data['Signal']
        signals['Histogram'] = macd_data['Histogram']

        # Tìm điểm giao cắt
        # MACD cắt lên Signal -> Tín hiệu mua
        signals.loc[
            (signals['MACD'] > signals['Signal']) &
            (signals['MACD'].shift(1) <= signals['Signal'].shift(1)),
            'signal'
        ] = 1

        # MACD cắt xuống Signal -> Tín hiệu bán
        signals.loc[
            (signals['MACD'] < signals['Signal']) &
            (signals['MACD'].shift(1) >= signals['Signal'].shift(1)),
            'signal'
        ] = -1

        return signals
2. Chiến lược Histogram
Sử dụng Histogram để xác định điểm vào lệnh sớm hơn.
class MACDHistogramStrategy:
    """
    Chiến lược dựa trên Histogram của MACD
    """

    def __init__(self, macd_indicator: MACDIndicator, threshold: float = 0.0001):
        self.macd_indicator = macd_indicator
        self.threshold = threshold  # Ngưỡng để xác nhận tín hiệu

    def generate_signals(self, data: pd.DataFrame) -> pd.DataFrame:
        """
        Tạo tín hiệu dựa trên Histogram
        """
        macd_data = self.macd_indicator.calculate(data['close'])

        signals = pd.DataFrame(index=data.index)
        signals['signal'] = 0
        signals['Histogram'] = macd_data['Histogram']
        signals['MACD'] = macd_data['MACD']
        signals['Signal'] = macd_data['Signal']

        # Tín hiệu mua: Histogram chuyển từ âm sang dương
        signals.loc[
            (signals['Histogram'] > 0) &
            (signals['Histogram'].shift(1) <= 0) &
            (signals['Histogram'] > self.threshold),
            'signal'
        ] = 1

        # Tín hiệu bán: Histogram chuyển từ dương sang âm
        signals.loc[
            (signals['Histogram'] < 0) &
            (signals['Histogram'].shift(1) >= 0) &
            (signals['Histogram'] < -self.threshold),
            'signal'
        ] = -1

        return signals
3. Chiến lược MACD với đường Zero
Kết hợp giao cắt với đường Zero để tăng độ chính xác.
class MACDZeroLineStrategy:
    """
    Chiến lược kết hợp giao cắt MACD/Signal và đường Zero
    """

    def __init__(self, macd_indicator: MACDIndicator):
        self.macd_indicator = macd_indicator

    def generate_signals(self, data: pd.DataFrame) -> pd.DataFrame:
        """
        Tạo tín hiệu với điều kiện MACD phải ở trên/dưới đường Zero
        """
        macd_data = self.macd_indicator.calculate(data['close'])

        signals = pd.DataFrame(index=data.index)
        signals['signal'] = 0
        signals['MACD'] = macd_data['MACD']
        signals['Signal'] = macd_data['Signal']
        signals['Histogram'] = macd_data['Histogram']

        # Tín hiệu mua: MACD cắt lên Signal VÀ MACD > 0
        buy_condition = (
            (signals['MACD'] > signals['Signal']) &
            (signals['MACD'].shift(1) <= signals['Signal'].shift(1)) &
            (signals['MACD'] > 0)
        )
        signals.loc[buy_condition, 'signal'] = 1

        # Tín hiệu bán: MACD cắt xuống Signal VÀ MACD < 0
        sell_condition = (
            (signals['MACD'] < signals['Signal']) &
            (signals['MACD'].shift(1) >= signals['Signal'].shift(1)) &
            (signals['MACD'] < 0)
        )
        signals.loc[sell_condition, 'signal'] = -1

        return signals
Xây dựng Bot Giao Dịch Forex
Lớp Forex Trading Bot
import ccxt
import time
import logging
from datetime import datetime
from typing import Optional, Dict

class ForexMACDBot:
    """
    Bot giao dịch Forex tự động sử dụng chiến lược MACD
    """

    def __init__(
        self,
        api_key: str,
        api_secret: str,
        exchange_name: str = 'binance',
        symbol: str = 'EUR/USDT',
        timeframe: str = '1h'
    ):
        """
        Khởi tạo bot

        Args:
            api_key: API key của sàn giao dịch
            api_secret: API secret của sàn giao dịch
            exchange_name: Tên sàn giao dịch (binance, oanda, etc.)
            symbol: Cặp tiền tệ (EUR/USDT, GBP/USD, etc.)
            timeframe: Khung thời gian ('1h', '4h', '1d')
        """
        self.api_key = api_key
        self.api_secret = api_secret
        self.symbol = symbol
        self.timeframe = timeframe

        # Khởi tạo exchange
        exchange_class = getattr(ccxt, exchange_name)
        self.exchange = exchange_class({
            'apiKey': self.api_key,
            'secret': self.api_secret,
            'enableRateLimit': True,
            'options': {
                'defaultType': 'spot'  # hoặc 'future' cho margin trading
            }
        })

        # Khởi tạo MACD indicator và strategy
        self.macd_indicator = MACDIndicator()
        self.strategy = MACDCrossoverStrategy(self.macd_indicator)

        # Quản lý vị thế
        self.position = None
        self.entry_price = None
        self.stop_loss = None
        self.take_profit = None

        # Cấu hình rủi ro
        self.risk_per_trade = 0.02  # 2% rủi ro mỗi lệnh
        self.stop_loss_pct = 0.02  # 2% stop loss
        self.take_profit_pct = 0.04  # 4% take profit

        # Logging
        logging.basicConfig(
            level=logging.INFO,
            format='%(asctime)s - %(levelname)s - %(message)s'
        )
        self.logger = logging.getLogger(__name__)

    def fetch_ohlcv_data(self, limit: int = 100) -> pd.DataFrame:
        """
        Lấy dữ liệu OHLCV từ sàn giao dịch

        Args:
            limit: Số lượng nến cần lấy

        Returns:
            DataFrame chứa dữ liệu OHLCV
        """
        try:
            ohlcv = self.exchange.fetch_ohlcv(
                self.symbol,
                self.timeframe,
                limit=limit
            )

            df = pd.DataFrame(
                ohlcv,
                columns=['timestamp', 'open', 'high', 'low', 'close', 'volume']
            )
            df['timestamp'] = pd.to_datetime(df['timestamp'], unit='ms')
            df.set_index('timestamp', inplace=True)

            return df

        except Exception as e:
            self.logger.error(f"Lỗi lấy dữ liệu: {str(e)}")
            return None

    def calculate_position_size(self, account_balance: float, entry_price: float) -> float:
        """
        Tính toán kích thước vị thế dựa trên rủi ro

        Args:
            account_balance: Số dư tài khoản
            entry_price: Giá vào lệnh

        Returns:
            Kích thước vị thế
        """
        risk_amount = account_balance * self.risk_per_trade
        stop_loss_distance = entry_price * self.stop_loss_pct

        if stop_loss_distance == 0:
            return 0

        position_size = risk_amount / stop_loss_distance

        return position_size

    def place_order(
        self,
        side: str,
        amount: float,
        order_type: str = 'market'
    ) -> Optional[Dict]:
        """
        Đặt lệnh giao dịch

        Args:
            side: 'buy' hoặc 'sell'
            amount: Số lượng
            order_type: Loại lệnh ('market', 'limit')

        Returns:
            Thông tin lệnh đã đặt
        """
        try:
            order = self.exchange.create_order(
                symbol=self.symbol,
                type=order_type,
                side=side,
                amount=amount
            )

            self.logger.info(f"Đã đặt lệnh {side.upper()}: {amount} {self.symbol}")
            return order

        except Exception as e:
            self.logger.error(f"Lỗi đặt lệnh: {str(e)}")
            return None

    def check_exit_conditions(self, current_price: float) -> bool:
        """
        Kiểm tra điều kiện thoát lệnh (stop loss, take profit)

        Args:
            current_price: Giá hiện tại

        Returns:
            True nếu cần thoát lệnh
        """
        if self.position is None:
            return False

        if self.position == 'long':
            # Kiểm tra stop loss
            if current_price <= self.stop_loss:
                self.logger.info(f"Kích hoạt Stop Loss tại {current_price}")
                return True

            # Kiểm tra take profit
            if current_price >= self.take_profit:
                self.logger.info(f"Kích hoạt Take Profit tại {current_price}")
                return True

        elif self.position == 'short':
            # Kiểm tra stop loss
            if current_price >= self.stop_loss:
                self.logger.info(f"Kích hoạt Stop Loss tại {current_price}")
                return True

            # Kiểm tra take profit
            if current_price <= self.take_profit:
                self.logger.info(f"Kích hoạt Take Profit tại {current_price}")
                return True

        return False

    def execute_trade(self, signal: int, current_price: float):
        """
        Thực hiện giao dịch dựa trên tín hiệu

        Args:
            signal: 1 (mua), -1 (bán), 0 (giữ)
            current_price: Giá hiện tại
        """
        # Kiểm tra điều kiện thoát lệnh trước
        if self.check_exit_conditions(current_price):
            self.close_position(current_price)
            return

        # Lấy số dư tài khoản
        try:
            balance = self.exchange.fetch_balance()
            account_balance = balance['total'].get('USDT', 0)
        except Exception as e:
            self.logger.error(f"Lỗi lấy số dư: {str(e)}")
            return

        # Xử lý tín hiệu mua
        if signal == 1 and self.position != 'long':
            # Đóng vị thế short nếu có
            if self.position == 'short':
                self.close_position(current_price)

            # Tính kích thước vị thế
            position_size = self.calculate_position_size(account_balance, current_price)

            if position_size > 0:
                # Đặt lệnh mua
                order = self.place_order('buy', position_size)

                if order:
                    self.position = 'long'
                    self.entry_price = current_price
                    self.stop_loss = current_price * (1 - self.stop_loss_pct)
                    self.take_profit = current_price * (1 + self.take_profit_pct)

                    self.logger.info(
                        f"Mở vị thế LONG: Entry={self.entry_price}, "
                        f"SL={self.stop_loss}, TP={self.take_profit}"
                    )

        # Xử lý tín hiệu bán
        elif signal == -1 and self.position != 'short':
            # Đóng vị thế long nếu có
            if self.position == 'long':
                self.close_position(current_price)

            # Tính kích thước vị thế
            position_size = self.calculate_position_size(account_balance, current_price)

            if position_size > 0:
                # Đặt lệnh bán
                order = self.place_order('sell', position_size)

                if order:
                    self.position = 'short'
                    self.entry_price = current_price
                    self.stop_loss = current_price * (1 + self.stop_loss_pct)
                    self.take_profit = current_price * (1 - self.take_profit_pct)

                    self.logger.info(
                        f"Mở vị thế SHORT: Entry={self.entry_price}, "
                        f"SL={self.stop_loss}, TP={self.take_profit}"
                    )

    def close_position(self, current_price: float):
        """
        Đóng vị thế hiện tại

        Args:
            current_price: Giá hiện tại
        """
        if self.position is None:
            return

        try:
            # Lấy số lượng vị thế hiện tại
            balance = self.exchange.fetch_balance()
            base_currency = self.symbol.split('/')[0]
            position_amount = balance['free'].get(base_currency, 0)

            if position_amount > 0:
                # Đóng lệnh
                if self.position == 'long':
                    self.place_order('sell', position_amount)
                else:
                    self.place_order('buy', position_amount)

                # Tính P&L
                if self.entry_price:
                    if self.position == 'long':
                        pnl_pct = ((current_price - self.entry_price) / self.entry_price) * 100
                    else:
                        pnl_pct = ((self.entry_price - current_price) / self.entry_price) * 100

                    self.logger.info(
                        f"Đóng vị thế {self.position.upper()}: "
                        f"Entry={self.entry_price}, Exit={current_price}, "
                        f"P&L={pnl_pct:.2f}%"
                    )

                # Reset vị thế
                self.position = None
                self.entry_price = None
                self.stop_loss = None
                self.take_profit = None

        except Exception as e:
            self.logger.error(f"Lỗi đóng vị thế: {str(e)}")

    def run(self):
        """
        Chạy bot giao dịch
        """
        self.logger.info(f"Khởi động bot giao dịch: {self.symbol}")

        while True:
            try:
                # Lấy dữ liệu thị trường
                data = self.fetch_ohlcv_data(limit=100)

                if data is None or len(data) < 50:
                    self.logger.warning("Không đủ dữ liệu, đợi chu kỳ tiếp theo...")
                    time.sleep(60)
                    continue

                # Tạo tín hiệu
                signals = self.strategy.generate_signals(data)
                latest_signal = signals['signal'].iloc[-1]
                current_price = data['close'].iloc[-1]

                # Thực hiện giao dịch
                if latest_signal != 0:
                    self.execute_trade(latest_signal, current_price)

                # Kiểm tra điều kiện thoát lệnh
                if self.position is not None:
                    self.check_exit_conditions(current_price)

                # Đợi đến chu kỳ tiếp theo
                time.sleep(60)  # Đợi 1 phút trước khi kiểm tra lại

            except KeyboardInterrupt:
                self.logger.info("Dừng bot theo yêu cầu người dùng")
                if self.position is not None:
                    data = self.fetch_ohlcv_data(limit=1)
                    if data is not None:
                        self.close_position(data['close'].iloc[-1])
                break

            except Exception as e:
                self.logger.error(f"Lỗi trong vòng lặp chính: {str(e)}")
                time.sleep(60)
Backtesting chiến lược MACD
Lớp Backtesting
class MACDBacktester:
    """
    Backtesting cho chiến lược MACD
    """

    def __init__(
        self,
        initial_capital: float = 10000,
        commission: float = 0.001  # 0.1% phí giao dịch
    ):
        self.initial_capital = initial_capital
        self.commission = commission
        self.capital = initial_capital
        self.position = None
        self.entry_price = None
        self.trades = []
        self.equity_curve = []

    def backtest(
        self,
        data: pd.DataFrame,
        strategy: MACDCrossoverStrategy
    ) -> pd.DataFrame:
        """
        Chạy backtest

        Args:
            data: Dữ liệu giá OHLCV
            strategy: Chiến lược giao dịch

        Returns:
            DataFrame chứa kết quả backtest
        """
        signals = strategy.generate_signals(data)

        results = data.copy()
        results['signal'] = signals['signal']
        results['MACD'] = signals['MACD']
        results['Signal'] = signals['Signal']
        results['position'] = 0
        results['capital'] = self.initial_capital
        results['returns'] = 0.0
        results['cumulative_returns'] = 0.0

        for i in range(1, len(results)):
            current_price = results['close'].iloc[i]
            signal = results['signal'].iloc[i]

            # Xử lý tín hiệu mua
            if signal == 1 and self.position != 'long':
                if self.position == 'short':
                    self._close_position(results, i, current_price)

                self.position = 'long'
                self.entry_price = current_price
                results.loc[results.index[i], 'position'] = 1

            # Xử lý tín hiệu bán
            elif signal == -1 and self.position != 'short':
                if self.position == 'long':
                    self._close_position(results, i, current_price)

                self.position = 'short'
                self.entry_price = current_price
                results.loc[results.index[i], 'position'] = -1

            # Tính toán lợi nhuận
            if self.position == 'long' and self.entry_price:
                pnl = ((current_price - self.entry_price) / self.entry_price) * self.capital
                results.loc[results.index[i], 'returns'] = pnl
            elif self.position == 'short' and self.entry_price:
                pnl = ((self.entry_price - current_price) / self.entry_price) * self.capital
                results.loc[results.index[i], 'returns'] = pnl

            # Tính cumulative returns
            results.loc[results.index[i], 'cumulative_returns'] = (
                results['returns'].iloc[:i+1].sum()
            )
            results.loc[results.index[i], 'capital'] = (
                self.initial_capital + results['cumulative_returns'].iloc[i]
            )

        # Đóng vị thế cuối cùng nếu còn
        if self.position is not None:
            self._close_position(results, len(results) - 1, results['close'].iloc[-1])

        return results

    def _close_position(self, results: pd.DataFrame, index: int, exit_price: float):
        """
        Đóng vị thế và tính P&L
        """
        if self.entry_price is None:
            return

        if self.position == 'long':
            pnl_pct = ((exit_price - self.entry_price) / self.entry_price) - self.commission
        else:
            pnl_pct = ((self.entry_price - exit_price) / self.entry_price) - self.commission

        pnl = pnl_pct * self.capital
        self.capital += pnl

        self.trades.append({
            'entry_time': results.index[index-1],
            'exit_time': results.index[index],
            'entry_price': self.entry_price,
            'exit_price': exit_price,
            'position': self.position,
            'pnl': pnl,
            'pnl_pct': pnl_pct * 100
        })

        self.position = None
        self.entry_price = None

    def calculate_metrics(self, results: pd.DataFrame) -> Dict:
        """
        Tính toán các chỉ số hiệu suất

        Args:
            results: Kết quả backtest

        Returns:
            Dictionary chứa các chỉ số
        """
        total_trades = len(self.trades)

        if total_trades == 0:
            return {
                'total_trades': 0,
                'win_rate': 0,
                'total_return': 0,
                'sharpe_ratio': 0
            }

        winning_trades = [t for t in self.trades if t['pnl'] > 0]
        losing_trades = [t for t in self.trades if t['pnl'] < 0]

        win_rate = len(winning_trades) / total_trades * 100

        total_return = ((self.capital - self.initial_capital) / self.initial_capital) * 100

        avg_win = np.mean([t['pnl'] for t in winning_trades]) if winning_trades else 0
        avg_loss = np.mean([t['pnl'] for t in losing_trades]) if losing_trades else 0

        profit_factor = abs(sum([t['pnl'] for t in winning_trades]) /
                          sum([t['pnl'] for t in losing_trades])) if losing_trades else 0

        # Tính Sharpe Ratio
        returns = results['returns'].dropna()
        if len(returns) > 0 and returns.std() > 0:
            sharpe_ratio = (returns.mean() / returns.std()) * np.sqrt(252)  # Annualized
        else:
            sharpe_ratio = 0

        # Maximum Drawdown
        cumulative = results['cumulative_returns']
        running_max = cumulative.expanding().max()
        drawdown = cumulative - running_max
        max_drawdown = drawdown.min()

        return {
            'total_trades': total_trades,
            'winning_trades': len(winning_trades),
            'losing_trades': len(losing_trades),
            'win_rate': win_rate,
            'total_return': total_return,
            'final_capital': self.capital,
            'avg_win': avg_win,
            'avg_loss': avg_loss,
            'profit_factor': profit_factor,
            'sharpe_ratio': sharpe_ratio,
            'max_drawdown': max_drawdown
        }
Ví dụ sử dụng Backtesting
# Ví dụ backtest
import yfinance as yf

# Lấy dữ liệu EUR/USD
data = yf.download('EURUSD=X', start='2023-01-01', end='2024-01-01', interval='1h')
data.columns = [col[0].lower() if isinstance(col, tuple) else col.lower()
                for col in data.columns]

# Chuẩn bị dữ liệu
data = data[['open', 'high', 'low', 'close', 'volume']].dropna()

# Khởi tạo strategy và backtester
macd_indicator = MACDIndicator()
strategy = MACDCrossoverStrategy(macd_indicator)
backtester = MACDBacktester(initial_capital=10000)

# Chạy backtest
results = backtester.backtest(data, strategy)

# Tính toán metrics
metrics = backtester.calculate_metrics(results)

print("=== Kết quả Backtest ===")
print(f"Tổng số lệnh: {metrics['total_trades']}")
print(f"Tỷ lệ thắng: {metrics['win_rate']:.2f}%")
print(f"Lợi nhuận tổng: {metrics['total_return']:.2f}%")
print(f"Sharpe Ratio: {metrics['sharpe_ratio']:.2f}")
print(f"Maximum Drawdown: {metrics['max_drawdown']:.2f}%")
print(f"Profit Factor: {metrics['profit_factor']:.2f}")
Tối ưu hóa tham số MACD
Grid Search để tìm tham số tối ưu
from itertools import product

class MACDOptimizer:
    """
    Tối ưu hóa tham số MACD
    """

    def __init__(self, data: pd.DataFrame):
        self.data = data
        self.best_params = None
        self.best_metrics = None

    def optimize(
        self,
        fast_range: range = range(8, 16),
        slow_range: range = range(20, 30),
        signal_range: range = range(6, 12)
    ) -> Dict:
        """
        Tìm tham số tối ưu bằng Grid Search

        Args:
            fast_range: Dải giá trị cho fast_period
            slow_range: Dải giá trị cho slow_period
            signal_range: Dải giá trị cho signal_period

        Returns:
            Dictionary chứa tham số tối ưu và metrics
        """
        best_sharpe = -np.inf
        best_params = None
        best_metrics = None

        total_combinations = len(list(product(fast_range, slow_range, signal_range)))
        print(f"Tổng số tổ hợp cần test: {total_combinations}")

        for fast, slow, signal in product(fast_range, slow_range, signal_range):
            if fast >= slow:
                continue

            try:
                # Khởi tạo indicator và strategy với tham số mới
                macd_indicator = MACDIndicator(
                    fast_period=fast,
                    slow_period=slow,
                    signal_period=signal
                )
                strategy = MACDCrossoverStrategy(macd_indicator)

                # Chạy backtest
                backtester = MACDBacktester(initial_capital=10000)
                results = backtester.backtest(self.data, strategy)
                metrics = backtester.calculate_metrics(results)

                # Đánh giá dựa trên Sharpe Ratio
                if metrics['sharpe_ratio'] > best_sharpe and metrics['total_trades'] > 10:
                    best_sharpe = metrics['sharpe_ratio']
                    best_params = {
                        'fast_period': fast,
                        'slow_period': slow,
                        'signal_period': signal
                    }
                    best_metrics = metrics

                    print(f"Tìm thấy tham số tốt hơn: {best_params}")
                    print(f"Sharpe Ratio: {best_sharpe:.2f}")

            except Exception as e:
                print(f"Lỗi với tham số ({fast}, {slow}, {signal}): {str(e)}")
                continue

        self.best_params = best_params
        self.best_metrics = best_metrics

        return {
            'best_params': best_params,
            'best_metrics': best_metrics
        }
Quản lý rủi ro nâng cao
Trailing Stop Loss
class TrailingStopLoss:
    """
    Trailing Stop Loss cho bot giao dịch
    """

    def __init__(self, trailing_pct: float = 0.02):
        """
        Args:
            trailing_pct: Phần trăm trailing stop (2% mặc định)
        """
        self.trailing_pct = trailing_pct
        self.highest_price = None  # Cho long position
        self.lowest_price = None   # Cho short position

    def update(self, current_price: float, position: str) -> Optional[float]:
        """
        Cập nhật trailing stop loss

        Args:
            current_price: Giá hiện tại
            position: 'long' hoặc 'short'

        Returns:
            Giá stop loss mới hoặc None
        """
        if position == 'long':
            if self.highest_price is None or current_price > self.highest_price:
                self.highest_price = current_price

            trailing_stop = self.highest_price * (1 - self.trailing_pct)
            return trailing_stop

        elif position == 'short':
            if self.lowest_price is None or current_price < self.lowest_price:
                self.lowest_price = current_price

            trailing_stop = self.lowest_price * (1 + self.trailing_pct)
            return trailing_stop

        return None
Position Sizing động
class DynamicPositionSizing:
    """
    Tính toán kích thước vị thế động dựa trên volatility
    """

    def __init__(self, base_risk: float = 0.02, lookback: int = 20):
        """
        Args:
            base_risk: Rủi ro cơ bản (2% mặc định)
            lookback: Số kỳ để tính volatility
        """
        self.base_risk = base_risk
        self.lookback = lookback

    def calculate_size(
        self,
        account_balance: float,
        entry_price: float,
        stop_loss_price: float,
        volatility: float
    ) -> float:
        """
        Tính kích thước vị thế dựa trên volatility

        Args:
            account_balance: Số dư tài khoản
            entry_price: Giá vào lệnh
            stop_loss_price: Giá stop loss
            volatility: Độ biến động (ATR hoặc std)

        Returns:
            Kích thước vị thế
        """
        # Điều chỉnh rủi ro dựa trên volatility
        # Volatility cao -> giảm kích thước vị thế
        volatility_factor = 1.0 / (1.0 + volatility)
        adjusted_risk = self.base_risk * volatility_factor

        # Tính kích thước vị thế
        risk_amount = account_balance * adjusted_risk
        stop_loss_distance = abs(entry_price - stop_loss_price)

        if stop_loss_distance == 0:
            return 0

        position_size = risk_amount / stop_loss_distance

        return position_size
Visualization và phân tích
Vẽ biểu đồ MACD
import matplotlib.pyplot as plt
import matplotlib.dates as mdates

def plot_macd_strategy(data: pd.DataFrame, signals: pd.DataFrame, results: pd.DataFrame = None):
    """
    Vẽ biểu đồ MACD và tín hiệu giao dịch

    Args:
        data: Dữ liệu giá
        signals: Tín hiệu giao dịch
        results: Kết quả backtest (optional)
    """
    fig, axes = plt.subplots(3, 1, figsize=(15, 12))

    # Biểu đồ giá
    ax1 = axes[0]
    ax1.plot(data.index, data['close'], label='Close Price', linewidth=1.5)

    # Đánh dấu điểm mua/bán
    buy_signals = signals[signals['signal'] == 1]
    sell_signals = signals[signals['signal'] == -1]

    ax1.scatter(buy_signals.index, data.loc[buy_signals.index, 'close'],
                color='green', marker='^', s=100, label='Buy Signal', zorder=5)
    ax1.scatter(sell_signals.index, data.loc[sell_signals.index, 'close'],
                color='red', marker='v', s=100, label='Sell Signal', zorder=5)

    ax1.set_title('Giá và Tín hiệu Giao dịch', fontsize=14, fontweight='bold')
    ax1.set_ylabel('Giá', fontsize=12)
    ax1.legend(loc='best')
    ax1.grid(True, alpha=0.3)

    # Biểu đồ MACD và Signal
    ax2 = axes[1]
    ax2.plot(signals.index, signals['MACD'], label='MACD', linewidth=1.5, color='blue')
    ax2.plot(signals.index, signals['Signal'], label='Signal', linewidth=1.5, color='red')
    ax2.axhline(y=0, color='black', linestyle='--', linewidth=0.5)
    ax2.set_title('MACD và Signal Line', fontsize=14, fontweight='bold')
    ax2.set_ylabel('MACD', fontsize=12)
    ax2.legend(loc='best')
    ax2.grid(True, alpha=0.3)

    # Biểu đồ Histogram
    ax3 = axes[2]
    colors = ['green' if x > 0 else 'red' for x in signals['Histogram']]
    ax3.bar(signals.index, signals['Histogram'], color=colors, alpha=0.6)
    ax3.axhline(y=0, color='black', linestyle='-', linewidth=0.5)
    ax3.set_title('MACD Histogram', fontsize=14, fontweight='bold')
    ax3.set_ylabel('Histogram', fontsize=12)
    ax3.set_xlabel('Thời gian', fontsize=12)
    ax3.grid(True, alpha=0.3)

    # Format x-axis
    for ax in axes:
        ax.xaxis.set_major_formatter(mdates.DateFormatter('%Y-%m-%d'))
        ax.xaxis.set_major_locator(mdates.DayLocator(interval=7))
        plt.setp(ax.xaxis.get_majorticklabels(), rotation=45)

    plt.tight_layout()
    plt.show()

    # Vẽ equity curve nếu có kết quả backtest
    if results is not None:
        fig, ax = plt.subplots(figsize=(15, 6))
        ax.plot(results.index, results['capital'], label='Equity Curve', linewidth=2)
        ax.axhline(y=backtester.initial_capital, color='red', linestyle='--',
                  label='Initial Capital', linewidth=1)
        ax.set_title('Equity Curve', fontsize=14, fontweight='bold')
        ax.set_ylabel('Vốn', fontsize=12)
        ax.set_xlabel('Thời gian', fontsize=12)
        ax.legend(loc='best')
        ax.grid(True, alpha=0.3)
        plt.tight_layout()
        plt.show()
Best Practices và Lưu ý
1. Kết hợp với các chỉ báo khác
MACD hoạt động tốt nhất khi kết hợp với các chỉ báo khác:
class EnhancedMACDStrategy:
    """
    Chiến lược MACD kết hợp với RSI và Volume
    """

    def __init__(self, macd_indicator: MACDIndicator):
        self.macd_indicator = macd_indicator

    def generate_signals(self, data: pd.DataFrame) -> pd.DataFrame:
        """
        Tạo tín hiệu với điều kiện bổ sung
        """
        # Tính MACD
        macd_data = self.macd_indicator.calculate(data['close'])

        # Tính RSI
        delta = data['close'].diff()
        gain = (delta.where(delta > 0, 0)).rolling(window=14).mean()
        loss = (-delta.where(delta < 0, 0)).rolling(window=14).mean()
        rs = gain / loss
        rsi = 100 - (100 / (1 + rs))

        signals = pd.DataFrame(index=data.index)
        signals['signal'] = 0
        signals['MACD'] = macd_data['MACD']
        signals['Signal'] = macd_data['Signal']
        signals['RSI'] = rsi

        # Tín hiệu mua: MACD cắt lên Signal VÀ RSI < 70 (không quá mua)
        buy_condition = (
            (signals['MACD'] > signals['Signal']) &
            (signals['MACD'].shift(1) <= signals['Signal'].shift(1)) &
            (signals['RSI'] < 70) &
            (signals['RSI'] > 30)  # Không quá bán
        )
        signals.loc[buy_condition, 'signal'] = 1

        # Tín hiệu bán: MACD cắt xuống Signal VÀ RSI > 30 (không quá bán)
        sell_condition = (
            (signals['MACD'] < signals['Signal']) &
            (signals['MACD'].shift(1) >= signals['Signal'].shift(1)) &
            (signals['RSI'] > 30) &
            (signals['RSI'] < 70)  # Không quá mua
        )
        signals.loc[sell_condition, 'signal'] = -1

        return signals
2. Quản lý thời gian giao dịch
from datetime import time

class TradingHoursFilter:
    """
    Lọc giao dịch theo giờ
    """

    def __init__(self, start_time: time, end_time: time):
        self.start_time = start_time
        self.end_time = end_time

    def is_trading_hours(self, timestamp: pd.Timestamp) -> bool:
        """
        Kiểm tra xem có trong giờ giao dịch không
        """
        current_time = timestamp.time()

        if self.start_time <= self.end_time:
            return self.start_time <= current_time <= self.end_time
        else:  # Qua đêm (ví dụ: 22:00 - 06:00)
            return current_time >= self.start_time or current_time <= self.end_time
3. Xử lý lỗi và logging
import logging
from logging.handlers import RotatingFileHandler

def setup_logging(log_file: str = 'forex_bot.log'):
    """
    Thiết lập logging cho bot
    """
    logger = logging.getLogger('ForexBot')
    logger.setLevel(logging.INFO)

    # File handler với rotation
    file_handler = RotatingFileHandler(
        log_file,
        maxBytes=10*1024*1024,  # 10MB
        backupCount=5
    )
    file_handler.setLevel(logging.INFO)

    # Console handler
    console_handler = logging.StreamHandler()
    console_handler.setLevel(logging.INFO)

    # Formatter
    formatter = logging.Formatter(
        '%(asctime)s - %(name)s - %(levelname)s - %(message)s'
    )
    file_handler.setFormatter(formatter)
    console_handler.setFormatter(formatter)

    logger.addHandler(file_handler)
    logger.addHandler(console_handler)

    return logger
Ví dụ hoàn chỉnh
Script chạy bot
# main.py
import os
from dotenv import load_dotenv

# Load environment variables
load_dotenv()

def main():
    # Cấu hình
    API_KEY = os.getenv('BINANCE_API_KEY')
    API_SECRET = os.getenv('BINANCE_API_SECRET')
    SYMBOL = 'EUR/USDT'
    TIMEFRAME = '1h'

    # Khởi tạo bot
    bot = ForexMACDBot(
        api_key=API_KEY,
        api_secret=API_SECRET,
        exchange_name='binance',
        symbol=SYMBOL,
        timeframe=TIMEFRAME
    )

    # Cấu hình rủi ro
    bot.risk_per_trade = 0.02  # 2% rủi ro mỗi lệnh
    bot.stop_loss_pct = 0.02   # 2% stop loss
    bot.take_profit_pct = 0.04  # 4% take profit (risk:reward = 1:2)

    # Chạy bot
    try:
        bot.run()
    except KeyboardInterrupt:
        print("nĐang dừng bot...")
        if bot.position is not None:
            data = bot.fetch_ohlcv_data(limit=1)
            if data is not None:
                bot.close_position(data['close'].iloc[-1])

if __name__ == '__main__':
    main()
File .env
BINANCE_API_KEY=your_api_key_here
BINANCE_API_SECRET=your_api_secret_here
Kết luận
Chiến lược MACD là một công cụ mạnh mẽ trong giao dịch Forex tự động. Tuy nhiên, để đạt được hiệu quả tốt, bạn cần:
- Backtest kỹ lưỡng: Luôn test chiến lược trên dữ liệu lịch sử trước khi triển khai
- Quản lý rủi ro: Sử dụng stop loss và position sizing phù hợp
- Kết hợp nhiều chỉ báo: MACD hoạt động tốt hơn khi kết hợp với RSI, Volume, v.v.
- Tối ưu tham số: Tìm tham số MACD phù hợp với từng cặp tiền tệ
- Giám sát liên tục: Bot cần được theo dõi và điều chỉnh định kỳ
Lưu ý quan trọng: Giao dịch Forex có rủi ro cao. Luôn sử dụng số tiền bạn có thể chấp nhận mất và không bao giờ đầu tư quá khả năng tài chính của mình.
Tài liệu tham khảo
Bài viết liên quan